
 LeasePoint Signal
Equipment interest → Full price → Payment objection
LeasePoint Signal
Bring financing into the conversation before price becomes the objection.
Signal helps sellers recognize when to introduce financing. It uses business and equipment details to explain a suggested next step, such as sharing an application or contacting a LeasePoint specialist.
Signal is not a consumer credit score, approval probability, prescreen, firm offer, pricing decision, or credit decision.
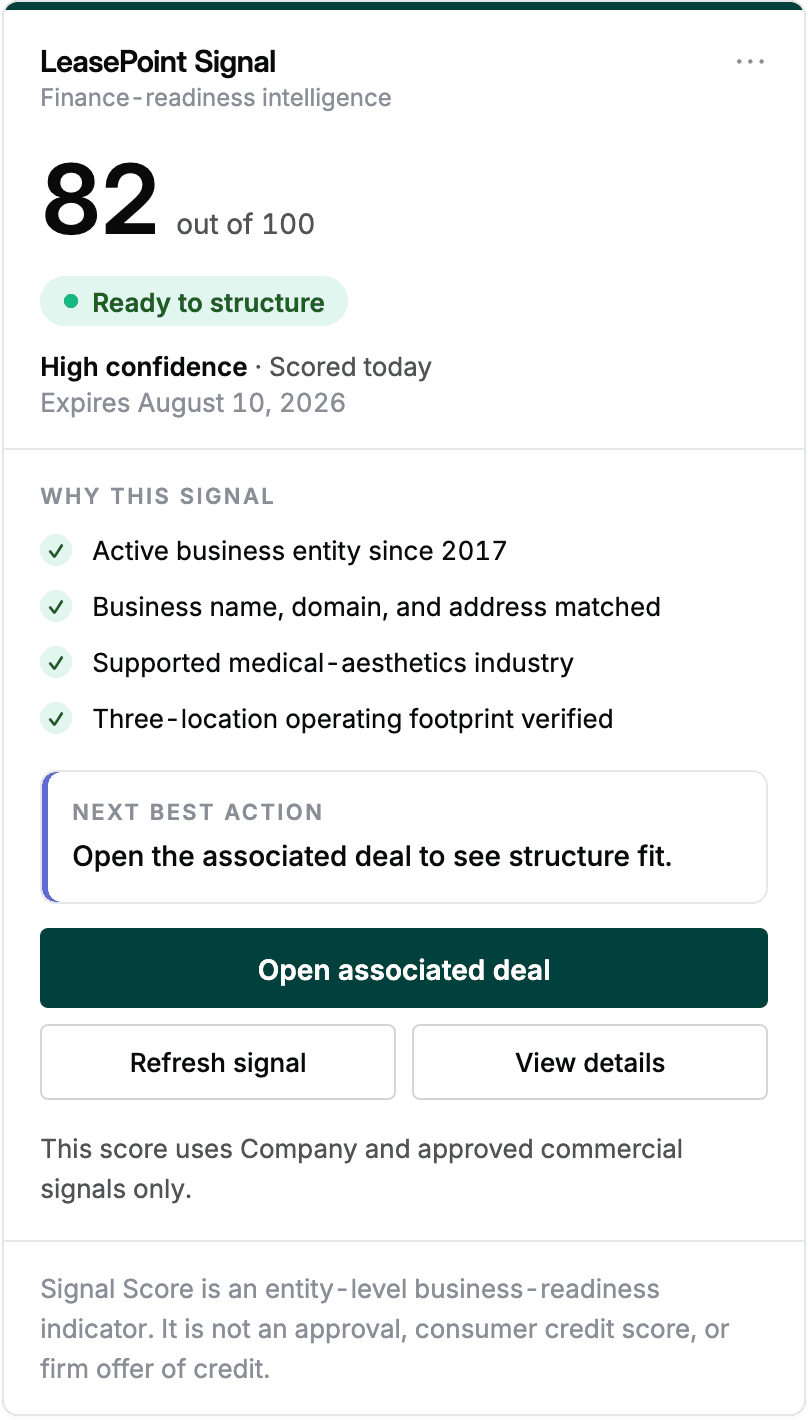
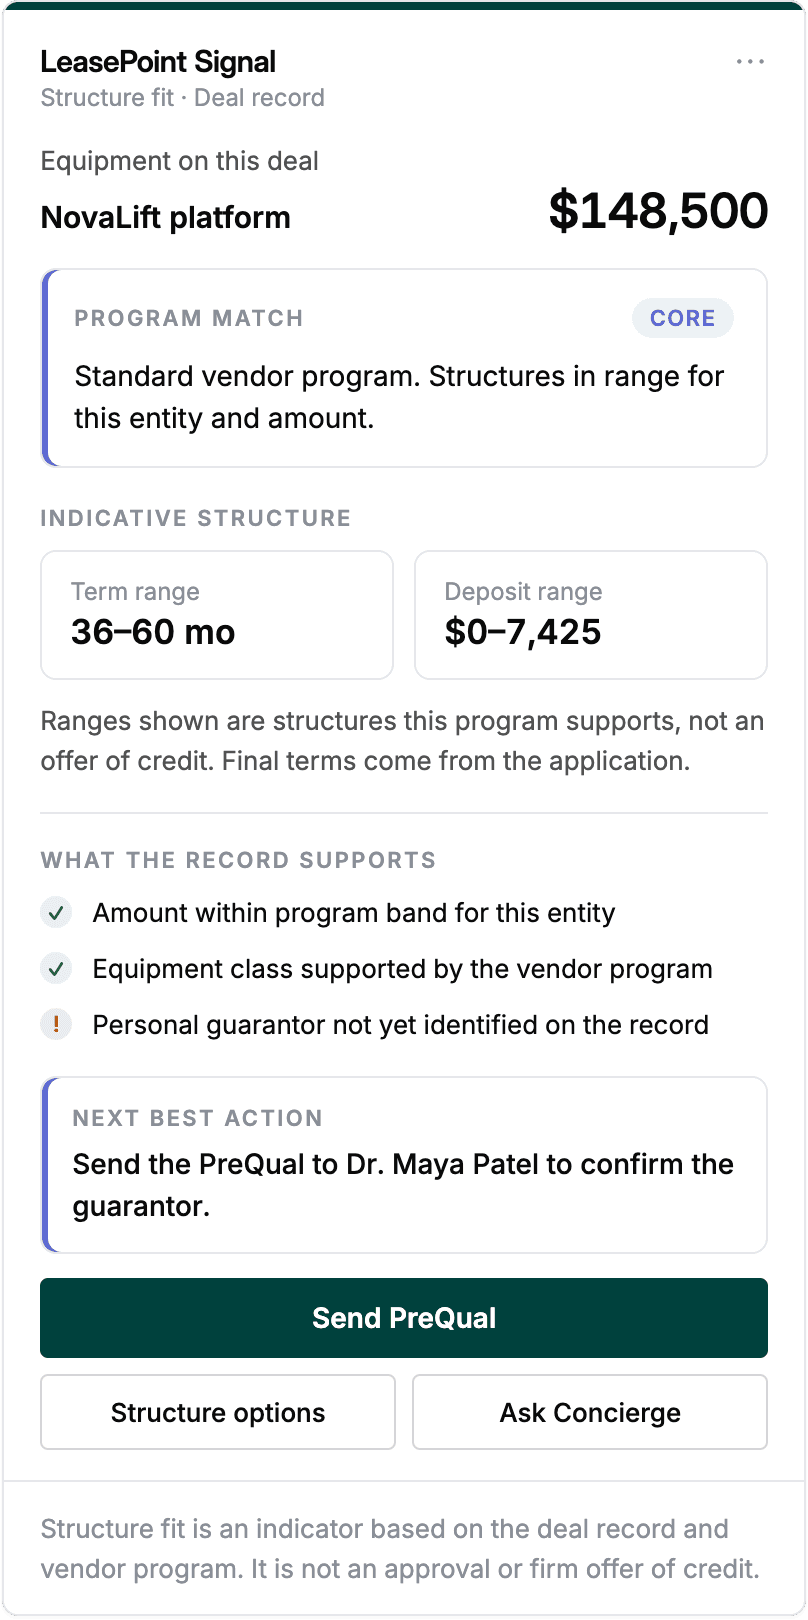
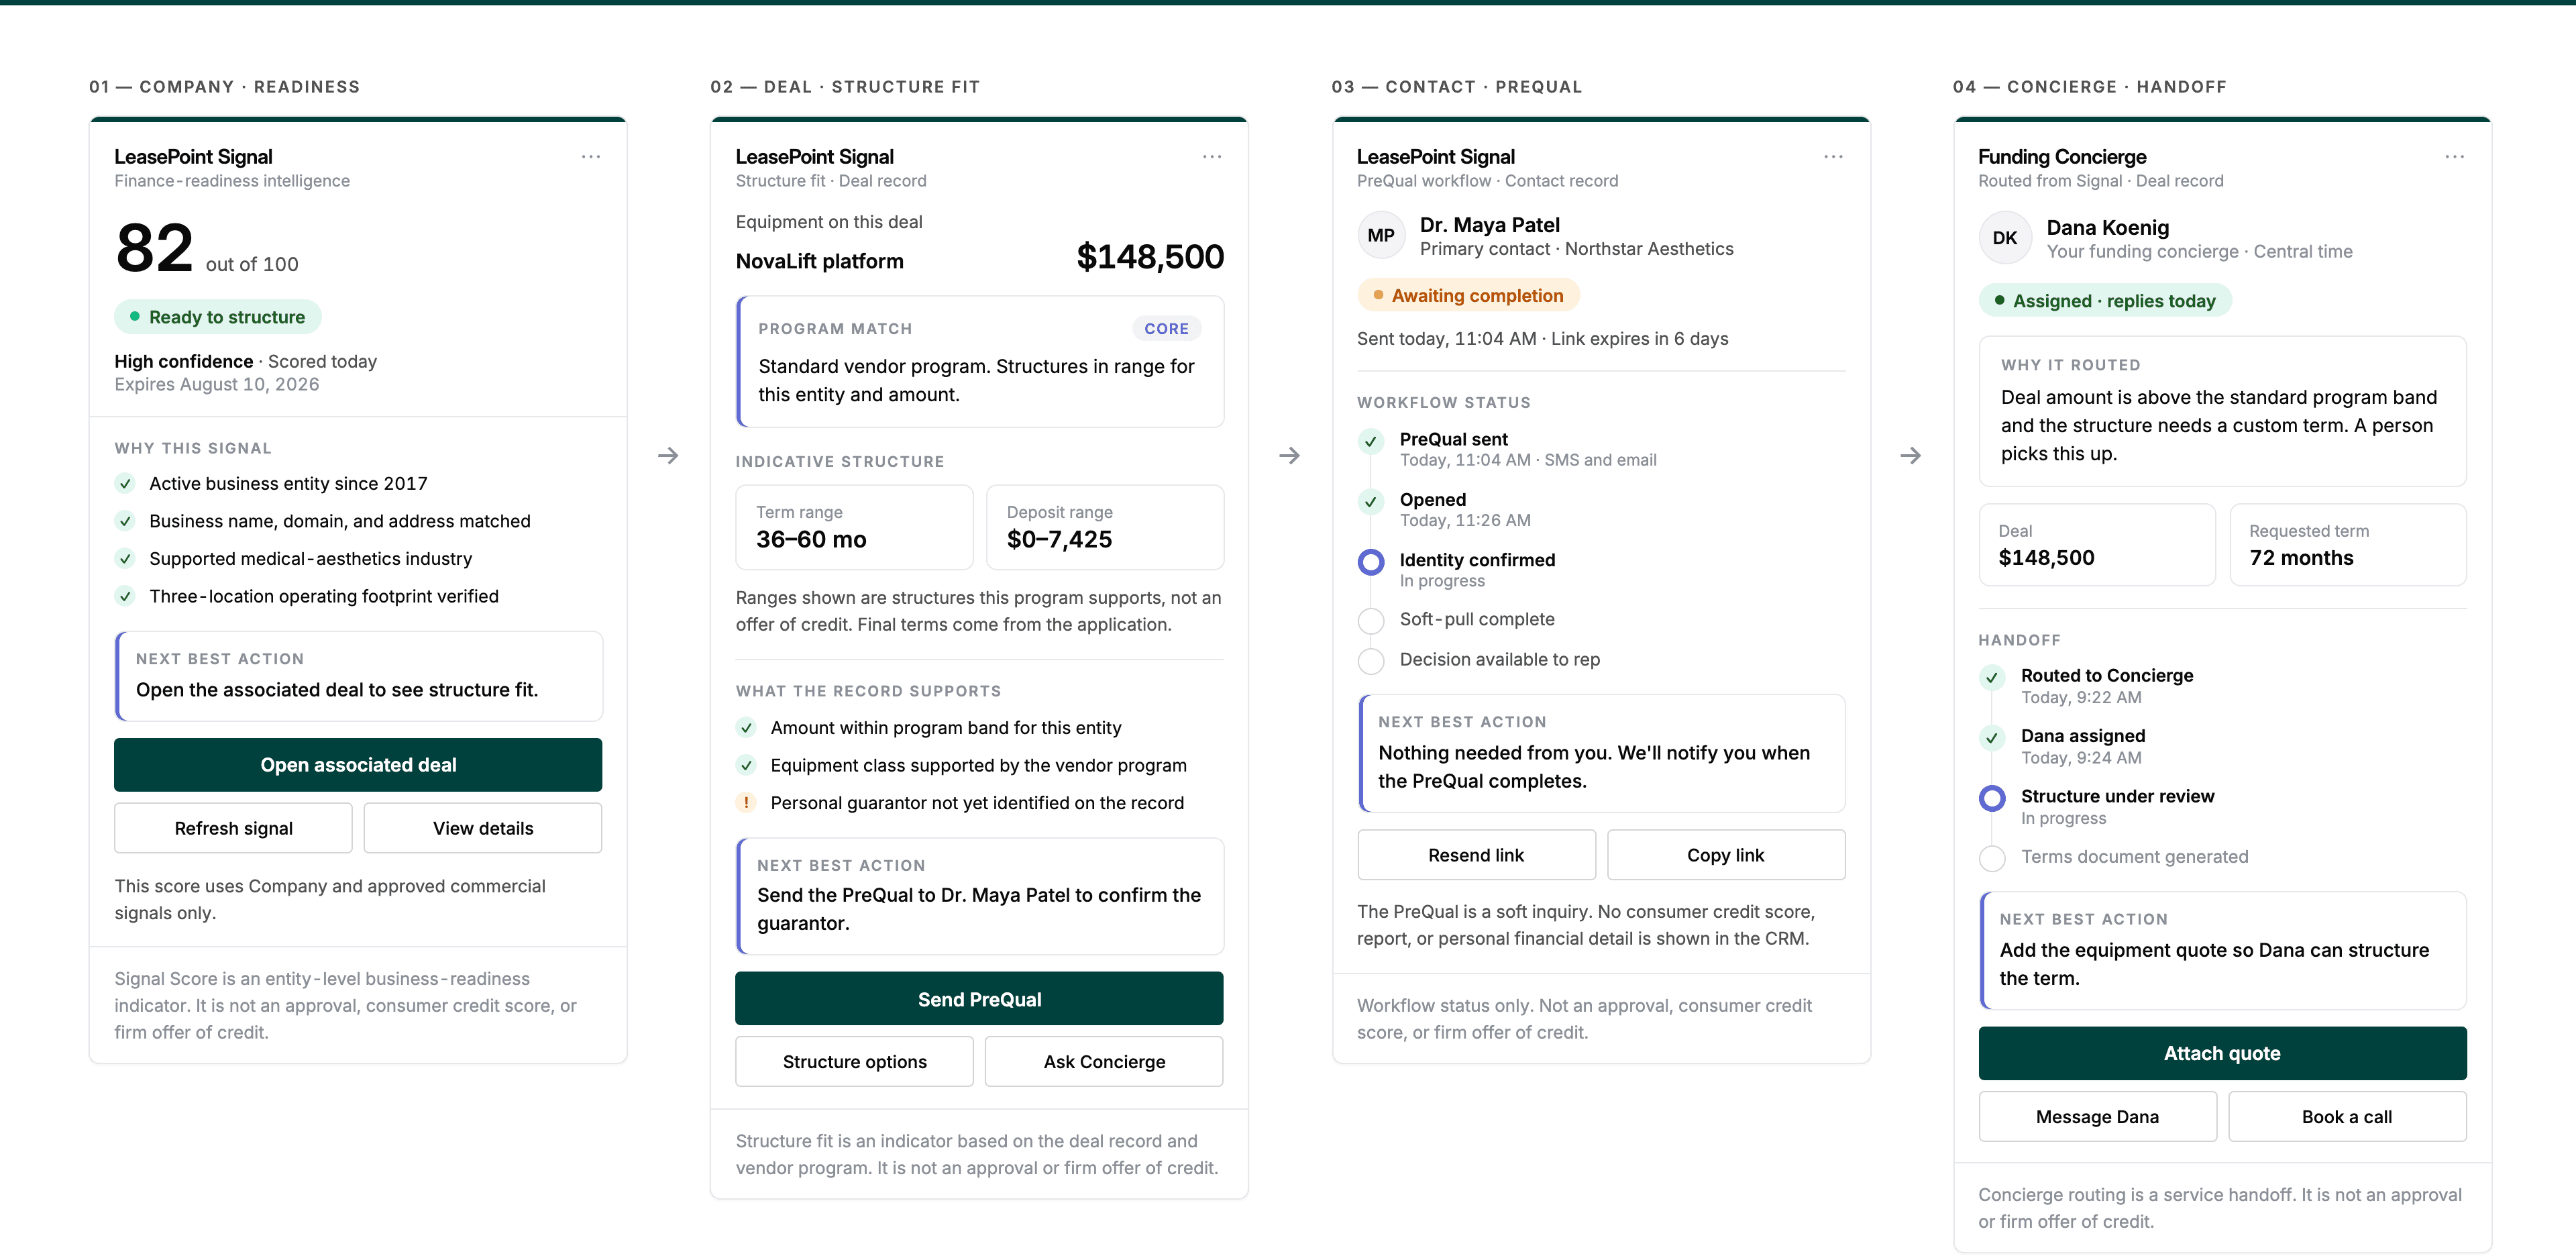
Illustrative product view. No real applicant, credit, or transaction data.
Start the conversation earlier
The financing conversation often starts too late.
A buyer may want the equipment and still have questions about how to pay for it. Signal helps your representative start that conversation and connect the buyer with LeasePoint.
Equipment interest → Approved context → Secure next step
What Signal gives the seller
Five outputs for one better financing conversation.
Context
A business-level view that helps an approved seller recognize where a payment conversation may be relevant.
Confidence
A plain-language indication of how complete and current the approved commercial context is, not approval likelihood.
Reason
An explainable summary of the business, equipment, opportunity, or program context behind the suggestion.
Program fit
A suggested approved conversation or route, not a rate, term, offer, or approval promise.
Next action
One practical move, such as introducing payment, sharing Apply, or involving Funding Concierge.
See the guidance change
See how Signal responds to different sales situations.
This demonstration changes the commercial explanation and next action while keeping the credit decision outside Signal.
LeasePoint SignalIllustrative guidance
Ready for a payment conversation
The buyer is reviewing the solution and budget needs useful context.
Next actionIntroduce a monthly-payment conversationOwner: Vendor representative
Signal guides a permitted commercial action. It does not approve, price, decline, or predict a transaction.
Illustrative product logic. Exact inputs, rules, outputs, roles, permissions, and availability depend on the approved program and implementation.
A responsible next step
Use approved context to guide the next action.
Read approved context
Use only the business, equipment, opportunity, and program information approved for seller guidance.
Explain the reason
Show why the context supports a financing conversation in plain sales language.
Recommend one action
Give the representative a responsible, program-approved next move.
Move securely
When the buyer wants to continue, route sensitive information through Apply or involve Funding Concierge.
Business context first
Useful context in the sales workflow. Applicant data in the secure system.
- Business identity and public company context
- Equipment category and transaction amount
- Opportunity stage and timing
- Seller or program context
- Data completeness and freshness
- Approved commercial indicators
- Context or readiness band
- Confidence in the approved commercial context
- Plain-language reason summary
- Suggested program fit
- One responsible next action
- Assessment freshness cue
- Secure invitation status
- Social Security numbers and dates of birth
- Consumer reports, scores, and bureau data
- Bank and account information
- Identity evidence and application documents
- Underwriting workpapers
- Adverse-action reasons
Value for the team
One seller signal. Different value for each responsible owner.
Vendor representative
See an explainable next step without interpreting credit policy.
Sales leader
Create a consistent financing motion that managers can coach and reinforce.
Revenue operations
Keep approved outputs, ownership, and freshness cues connected to the opportunity workflow.
Program owner
Review whether the team recognizes the finance moment and uses the approved next step.
Compliance and security
Separate commercial guidance from consumer credit and restricted information.
Signal in a program
Start with a focused seller group. Scale when the operating evidence supports it.
A focused 90-day pilot
Use Signal with one equipment category or seller group, then review participation, introductions, workflow friction, and the next program decision.
Review LaunchA repeatable portfolio-wide motion
Connect seller guidance, Apply, Partner, Funding Concierge, and recurring operating reviews across the approved organization.
Review CoreConnected by responsible handoffs
Signal starts the motion. Apply, Partner, and Funding Concierge carry it forward.
Signal
Guide the seller with approved context and one responsible next action.
Current page
Apply
Give the buyer a clear, secure route to provide applicable information.
Explore Apply
Partner
Share relevant transaction updates and follow-up tasks.
Explore Partner
Funding Concierge
Bring in a person when a question needs explanation, coordination, or judgment.
Explore Funding ConciergeEquipment finance focusBuilt around commercial equipment sales
Role-based viewsUseful context follows responsibility
Human supportFunding Concierge remains in the workflow
Program configuredAvailability follows the approved scope
Frequently asked questions
Understand Signal before you map the workflow.
Is Signal a credit score?
No. Signal presents approved business and opportunity context for the seller workflow. It is not a consumer credit score, bureau score, or underwriting score.
Does a positive Signal mean the buyer will be approved?
No. Signal does not predict or promise a credit result. Every transaction follows the applicable review, approval, documentation, and funding requirements.
Does Signal contain consumer credit information?
It should not. Applicant identity, consumer report, banking, personal document, and underwriting information belongs in approved restricted systems.
Can a representative send the buyer to Apply?
When the approved program permits it, Signal can present a secure Apply route or another responsible next action.
Can Signal work with a CRM?
Specific integration availability depends on the approved implementation and must be verified before publication or rollout.
What happens when the opportunity does not fit the standard path?
Signal can direct the representative to Funding Concierge or a Flex structure review when the program permits that route.
Does Signal automatically deny opportunities?
No. Signal does not make or communicate a credit decision. It guides an approved commercial next action while accountable finance teams retain review and decision responsibility.
Equip the seller motion
Give the team one responsible next action when financing becomes relevant.
Bring the seller workflow, equipment category, current CRM process, and program ownership. LeasePoint will help identify where Signal belongs and what must be approved before rollout.